
Allocating estate property values correctly means using the fair market value (FMV) at the decedent's date of death, splitting that FMV between non-depreciable land and depreciable improvements, and documenting every step with a method the IRS can verify. IRS Publication 551 is the foundational authority; Form 706 and Schedule A (Form 8971) set the values beneficiaries must use as their initial basis when an estate tax return is filed.
Three actions to take right now:
- Commission a date-of-death retrospective appraisal that explicitly separates land value from building/improvement value.
- Allocate land vs. improvements using a defensible method (USPAP-compliant appraisal, assessor ratio with documentation, or cost approach where appropriate).
- Document everything with a USPAP-compliant appraisal report, assessor records, and any Form 706/Schedule A filed with the IRS.
If you're an executor or attorney in New Jersey and need a state-certified date-of-death appraisal, Newjerseyrealestateappraisal handles exactly this. Read the full steps below before you file anything.
Key Takeaways
Proper estate property allocation requires a date-of-death FMV, a documented land/improvement split, and consistent reporting across the appraisal, Form 706, and Schedule A delivered to beneficiaries.
| Point | Details |
|---|---|
| Step-up in basis | Inherited property basis resets to FMV at date of death, eliminating prior capital gains. |
| Land vs. improvements split | Only the improvements portion is depreciable; use a USPAP appraisal or documented assessor ratio to establish the split. |
| Depreciation reset | Beneficiaries start a new depreciation schedule (27.5 years residential, 39 years commercial) using the stepped-up building basis. |
| Form 706 and Schedule A | When Form 706 is filed, Schedule A (Form 8971) values are binding on beneficiaries as their initial basis. |
| Newjerseyrealestateappraisal | NJREAG provides state-certified, court-ready date-of-death appraisals across all 21 NJ counties with explicit land/improvement breakouts for defensible estate allocations. |
Table of Contents
- What is an estate property allocation guide, and which IRS rules govern it?
- How do you allocate a single property's FMV between land and improvements?
- Which valuation approach should you use for a date-of-death appraisal?
- Which portion of an inherited property can you depreciate, and how?
- What are the filing steps for executors and beneficiaries?
- How does estate tax apportionment work with out-of-state property?
- What mistakes trigger IRS scrutiny, and what documentation do you need?
- Why does a USPAP-compliant date-of-death appraisal matter most?
- How do debts and liabilities affect estate property allocation?
- How does ownership structure affect property allocation?
- What are the tax implications for beneficiaries who receive allocated property?
- What property allocation strategies can reduce estate tax?
- What are the special rules for properties with conservation easements?
- How do you handle heir disputes over property valuation and allocation?
- Newjerseyrealestateappraisal delivers court-ready estate appraisals across New Jersey
- Sources
What is an estate property allocation guide, and which IRS rules govern it?
Inherited property generally receives a step-up in basis to FMV at the decedent's date of death. That single rule, confirmed by Publication 551, resets the tax clock for beneficiaries and eliminates capital gains that accrued during the decedent's lifetime. The step-up applies to the entire property, but the allocation between land and improvements is what determines how much of that stepped-up basis is actually depreciable.
Key terms and forms every executor needs:
- Step-up in basis: The beneficiary's starting basis equals the FMV at date of death, not the decedent's original purchase price.
- Alternate valuation election: Under Form 706 instructions, an executor may elect to value the estate six months after the date of death if doing so reduces both the gross estate value and the estate tax. The election must reduce both; it cannot be used selectively. Once made, it applies to all estate assets.
- Form 706: The federal estate tax return. Values reported here are binding on beneficiaries when the return is filed.
- Form 8971 / Schedule A: When Form 706 is required, executors must furnish beneficiaries with Schedule A, which reports the estate tax value for each distributed property. Beneficiaries generally must use that value as their initial basis.
- Publication 551: The IRS's primary guidance on basis, adjusted basis, and allocation between land and buildings. About Publication 551 confirms it remains current guidance.
- Publication 561: Covers valuation approaches and appraiser qualifications for substantiating value conclusions.
When Form 706 is filed, the executor supplies basis information to each beneficiary via Schedule A. That figure is not optional for the beneficiary to override without an official correction. If the estate does not owe federal estate tax and Form 706 is not required, the step-up still applies, but the basis is established by the appraisal or other acceptable evidence rather than a filed return.
How do you allocate a single property's FMV between land and improvements?
The FMV of an inherited property must be split into two components: land (non-depreciable) and building or improvements (depreciable). You need a documented, defensible method for that split. The IRS does not accept a single lump-sum FMV as a fully depreciable basis.
Methods in order of defensibility:
- Retrospective date-of-death appraisal with explicit land/improvement breakout. This is the strongest evidence. A state-certified appraiser values the property as of the date of death and states the land and building values separately in the report.
- Local property-tax assessor ratios. Most county assessors break assessed value into land and improvement components. You can apply that ratio to the appraised FMV. For example, if the assessor shows land at 20% and improvements at 80% of assessed value, apply those percentages to the total FMV.
- Insurance replacement-cost proxy. The insured replacement cost of the structure (excluding land) can support an improvement allocation, particularly for unique or specialty properties.
- Allocation by agreement. In limited cases, an allocation supported by contract or written agreement among parties may be accepted, but only when backed by independent evidence.
Worked example:
A residential rental property has a date-of-death FMV of $600,000. Applying that ratio:
- Land basis: $600,000 × 20% = $120,000 (non-depreciable)
- Building basis: $600,000 × 80% = $480,000 (depreciable over 27.5 years)
Annual straight-line depreciation is calculated by dividing the building basis by the applicable recovery period for residential rental property, typically 27.5 years, resulting in the depreciation amount per year.
Pro Tip: For high-value estates, properties in contested probate, or any situation with audit risk, skip the assessor-ratio shortcut and commission a retrospective USPAP-compliant appraisal. The appraiser's reconciled opinion of land vs. improvements, supported by market evidence as of the date of death, is far more defensible than a ratio derived from a tax assessment that may be years out of date.
Assessor ratios are convenient and the IRS acknowledges them in limited contexts, but they reflect the assessor's mass-appraisal methodology, not a property-specific analysis of condition, highest-and-best-use, or market conditions as of the exact date of death. For a high-value NJ estate in Bergen County or Morris County, that distinction can mean tens of thousands of dollars in depreciation basis.
Which valuation approach should you use for a date-of-death appraisal?
Use the approach (or combination of approaches) that best reflects the property's highest-and-best-use and market conditions as of the date of death. IRM 4.48.6 requires appraisers and IRS examiners to document scope, justify methodology selection, and reconcile approaches. Choosing a method because it's convenient, rather than because it fits the property type, is one of the fastest ways to invite scrutiny.
| Approach | What it measures | Typical inputs | Best for estate work when... |
|---|---|---|---|
| Market (Sales Comparison) | Price a willing buyer would pay based on recent comparable sales | Adjusted comparable sales near the date of death | Single-family residential, standard condos, typical commercial |
| Income | Present value of future income stream | Rent rolls, vacancy rates, cap rates as of date of death | Income-producing properties: rentals, multi-family, commercial leases |
| Cost | Depreciated replacement cost of improvements plus land value | Replacement cost new, accrued depreciation, land value | Specialty or unique properties with few comparables; new construction |
A retrospective date-of-death appraisal differs from a loan appraisal or a pre-listing appraisal in one critical way: the effective date is fixed in the past. The appraiser must reconstruct market conditions as they existed on that specific date, using sales data, listings, and economic indicators from that period. IRS examiners scrutinize inconsistent methods or inputs, and IRM 4.48.6 makes clear that the reconciliation of approaches must be documented and justified.
Publication 561 reinforces that appraiser qualifications and documentation are not optional. An appraiser who cannot explain why they chose one approach over another, or who fails to reconcile conflicting value indicators, produces a report that won't hold up under examination. When the IRS engages its own outside fee appraisal process for complex assets, it follows the same documentation standards it expects from taxpayers.
Which portion of an inherited property can you depreciate, and how?
Only the improvements portion of the stepped-up basis is depreciable. Land never depreciates. Under MACRS (Modified Accelerated Cost Recovery System), the recovery periods are:
- Residential rental property: 27.5 years, straight-line
- Commercial real property: 39 years, straight-line
Publication 551 confirms that for inherited rental property, the FMV must be allocated between land and depreciable improvements, and depreciation begins when the beneficiary places the property in service.
Depreciation reset at inheritance:
Many executors mistakenly allow beneficiaries to continue the decedent's existing depreciation schedule. That's wrong. When property is inherited, the beneficiary starts a completely new depreciation schedule using the stepped-up building basis. Practitioners call this the "depreciation reset." The prior owner's accumulated depreciation is irrelevant to the beneficiary's calculation.
Key rules for beneficiaries:
- Depreciation begins on the placed-in-service date for the beneficiary, which is when the property is available for rent or business use after the estate transfer, not the date of death itself.
- If the property sits vacant after transfer while the estate is being settled, depreciation does not begin until the beneficiary makes it available for its intended use.
- Capital improvements made after the date of death are added to basis and depreciated separately, not folded into the inherited building basis.
Pro Tip: Document the placed-in-service date with a written record: the date the property was listed for rent, a lease agreement, or a written statement from the executor. The IRS can challenge depreciation that starts before the property was actually available for use.
Depreciation recapture on later sale:
The step-up at death does not eliminate future recapture on depreciation the beneficiary actually claims. This is a meaningful tax planning consideration, particularly for high-value NJ rental properties.
What are the filing steps for executors and beneficiaries?
If Form 706 is required, the values on that return set the initial basis for beneficiaries. Executors must provide accurate documentation and deliver Schedule A (Form 8971) to each beneficiary. Getting this wrong creates basis inconsistencies that can surface years later when a beneficiary sells.
Key filing timeline:
| Task | Deadline / Timing |
|---|---|
| Form 706 filing | Generally within the executor's filing deadline, with possible extensions available |
| Alternate valuation election | Must be made on a timely filed Form 706 (including extensions) |
| Schedule A (Form 8971) delivery to beneficiaries | Generally due when Form 706 is filed or shortly after distribution |
| Alternate valuation election revocation | Can be revoked before the due date of the return (including extensions) |
Executor checklist:
- Obtain a date-of-death retrospective appraisal with a land/improvement breakout.
- Decide whether to elect alternate valuation (it must reduce both gross estate value and estate tax).
- Prepare and file Form 706 using the appraised values.
- Deliver Schedule A (Form 8971) to each beneficiary with the estate tax value for their distributed property.
- Retain the appraisal report, workpapers, assessor records, and all supporting documentation.
About Form 8971 makes clear that beneficiaries generally must use the Schedule A value as their initial basis. If the executor later discovers an error in the reported value, an amended Form 706 and corrected Schedule A should be filed before the beneficiary files a return using the incorrect basis.
A protective alternate valuation election can be made on a timely filed return even when the executor is uncertain whether it will reduce both the gross estate and the tax. If it turns out the conditions aren't met, the election is simply disregarded. Consult your estate attorney or CPA before making or revoking this election.
How does estate tax apportionment work with out-of-state property?
When an estate includes real property in multiple states, the calculation gets more complex and the risk of misallocation increases.
New Jersey follows its own estate tax rules, and each state where real property is located may impose its own estate or inheritance tax. An executor managing a New Jersey estate that includes a vacation property in another state must check that state's apportionment rules separately.
A simplified apportionment illustration (not legal advice):
State rules and the estate instrument may modify this calculation significantly.
Action items for multi-state estates:
- Identify every state where real property is located and check that state's apportionment statute or common law rule.
- Coordinate with local counsel in each state; do not assume New Jersey's rules apply elsewhere.
- Consider the timing of property sales relative to estate tax deadlines, since a sale before the estate is closed can affect apportionment calculations.
- Obtain separate, jurisdiction-specific appraisals when market conditions differ materially between states. An appraiser familiar with NJ suburban markets is not necessarily qualified to value a property in another state's market.
For deed-based transfers in other states, the transfer-on-death deed framework used in states like Texas illustrates how title-transfer mechanisms can affect which assets pass through probate and how apportionment is calculated. NJ does not currently recognize transfer-on-death deeds for real property, so this is a multi-jurisdictional planning point, not an NJ-specific option.
What mistakes trigger IRS scrutiny, and what documentation do you need?
The most common pitfall is treating the entire FMV as depreciable. A close second is using a loan appraisal or pre-listing appraisal instead of a retrospective date-of-death appraisal. Both errors can result in IRS adjustments, penalties, and disputes among heirs that could have been avoided with proper documentation from the start.
Documentation checklist:
- Date-of-death retrospective appraisal report with explicit land and building/improvement values
- Deeds and title transfer documents
- Probate inventory listing all estate assets
- Form 706 and Schedule A (Form 8971), if filed
- Assessor records with date stamps showing the land/improvement breakdown
- Receipts and records for capital improvements made after the date of death
- Insurance replacement cost documentation where used to support improvement allocation
- Workpapers showing how the allocation was calculated
Red flags that invite IRS scrutiny:
- Inconsistent appraisals (different values for the same property in different filings)
- Last-minute changes to allocations after the estate tax return is prepared
- Assessor-only allocations for high-value estates with no independent appraisal support
- Depreciation schedules that continue the decedent's prior schedule rather than resetting at the stepped-up basis
- Missing or incomplete Schedule A delivery to beneficiaries
Keeping complete workpapers is not optional for high-value estates.
For a practical recordkeeping framework, the executor's guide to appraisal records covers what to retain and how to organize documentation for NJ probate matters.
Why does a USPAP-compliant date-of-death appraisal matter most?
A USPAP-compliant, retrospective date-of-death appraisal by a state-certified appraiser is the most defensible evidence you can produce for allocation and depreciation basis. It's not just a formality. It's the document that stands between your allocation and an IRS adjustment.
What to require in the appraisal report:
- A clearly stated effective date equal to the date of death
- Separate land and improvement values, not just a total FMV
- A written explanation of the methodology used and why it was selected
- Comparable sales or income modeling as of the date of death (not current market data)
- A reconciled opinion of value that addresses any divergence between approaches
- Appraiser certification of USPAP compliance and state certification credentials
USPAP compliance is not negotiable. The Uniform Standards of Professional Appraisal Practice sets the minimum standards for appraisal reports used in federal tax matters. An appraiser who is not state-certified or who does not follow USPAP produces a report the IRS can reject outright. For NJ estates, that means working with a New Jersey state-certified appraiser.
Pro Tip: Ask the appraiser directly: "Will this report include a separate land value and building value, and will it state the effective date as the date of death?" If the answer is anything other than yes, find a different appraiser.
For a detailed walkthrough of the date-of-death appraisal process in NJ, including what to expect from the inspection and report delivery, Newjerseyrealestateappraisal has published a step-by-step guide for executors.
Typical timeline and cost ranges for estate appraisals
A typical estate appraisal in New Jersey runs 2–8 weeks from initial intake to final report delivery, depending on property complexity and the availability of comparable sales data near the date of death.
Timeline breakdown:
- Week 1: Initial intake, records gathering, deed review, assessor data
- Weeks 1–3: Property inspection, market research, comparable sales analysis as of the date of death
- Weeks 2–4: Draft report preparation and internal review
- Week 4–8: Final report delivery; complex or multi-property estates take longer
Form 706 preparation by a CPA or estate attorney runs in parallel with the appraisal process. Executors should commission the appraisal as early as possible to avoid compressing the filing timeline.
Cost ranges for NJ estate/date-of-death appraisals (typical market ranges, not guarantees):
- Residential single-family: $500–$900 for a standard report
- Multi-family (2–4 units): $700–$1,200
- Commercial or complex properties: $1,500 and up, depending on scope
Filing deadline reminder: Form 706 is generally due nine months after the date of death, with a six-month extension available. The alternate valuation election must be made on a timely filed return. Consult your estate attorney or CPA for deadlines specific to your estate.
How do debts and liabilities affect estate property allocation?
Debts and liabilities reduce the taxable estate but do not directly reduce the FMV of individual properties for allocation purposes. The FMV of each property is still determined independently as of the date of death. A mortgage on an inherited property does not lower the property's FMV for basis purposes; it affects the net estate value and the estate tax calculation, not the beneficiary's stepped-up basis.
When a beneficiary inherits a property subject to a mortgage, the basis is still the full FMV at date of death, not the equity. If the estate pays off the mortgage from other assets, that affects the estate's net value but not the property's allocated basis. If the beneficiary assumes the mortgage, the basis remains the full FMV.
Deductible debts, mortgages, and liens are reported on Form 706 as deductions from the gross estate. Executors should work with a CPA to ensure that liabilities are properly documented and deducted, since errors here affect the estate tax calculation and, indirectly, the alternate valuation election analysis.
How does ownership structure affect property allocation?
The type of ownership interest the decedent held determines what portion of the property is included in the gross estate and how the step-up in basis applies.
For joint tenancy between non-spouses, the full value is included in the decedent's estate unless the survivor can prove their contribution to the purchase price.
Tenancy in common: Each owner holds a defined fractional interest. Only the decedent's fractional share is included in the gross estate, and the step-up applies only to that share. The surviving co-owners retain their original basis in their shares.
Community property: New Jersey is not a community property state, but executors managing estates with property in community property states (California, Texas, Arizona, and others) should note that both halves of community property generally receive a step-up at the death of either spouse. This is a significant basis advantage compared to JTWROS in common-law states.
Tenancy by the entirety: Available in New Jersey for married couples, this functions similarly to JTWROS for estate purposes.
The ownership structure must be confirmed from the deed before the appraisal is ordered, since it determines the scope of the valuation and the allocation.
What are the tax implications for beneficiaries who receive allocated property?
Beneficiaries generally owe no income tax on the property they receive from an estate. The step-up in basis means that if they sell immediately at FMV, the capital gain is zero. The tax implications arise later, based on what the beneficiary does with the property.
If the beneficiary sells the property: Capital gains are calculated from the stepped-up basis. A sale price above the stepped-up FMV produces a taxable gain; a sale below produces a loss. Gains on property held more than one year are taxed at long-term capital gains rates.
If the beneficiary rents the property: Rental income is taxable, and the beneficiary may deduct depreciation on the building portion of the stepped-up basis. This is where the land/improvement allocation directly affects annual tax liability.
If the beneficiary holds the property for personal use: No depreciation is available, and the basis simply carries forward until a future sale.
Estate and inheritance taxes: New Jersey currently imposes an inheritance tax on transfers to certain beneficiaries (Class C and D beneficiaries, which include siblings, nieces, nephews, and unrelated individuals). Transfers to direct descendants and spouses are exempt from NJ inheritance tax. Executors should confirm the beneficiary classification with an estate attorney before distribution.
This is general information, not legal or tax advice. Confirm current NJ inheritance tax rules and federal estate tax thresholds with a qualified estate attorney or CPA.
What property allocation strategies can reduce estate tax?
Several legitimate strategies use property allocation and valuation to reduce the taxable estate. None of them involve misrepresenting value; they work by structuring ownership and timing to take advantage of existing tax rules.
Fractional interest discounts: When a property is held in a tenancy in common or through an entity like an LLC, the decedent's fractional interest may be valued at a discount to its pro-rata share of the whole property's FMV. Minority interest and lack-of-marketability discounts are recognized by the IRS when properly supported by a qualified appraisal. These discounts can meaningfully reduce the gross estate value.
Alternate valuation election: If property values declined between the date of death and six months later, the alternate valuation election under Form 706 instructions can reduce the taxable estate. The election must reduce both the gross estate and the estate tax, and it applies to all estate assets, not just the ones that declined.
Charitable remainder trusts and conservation easements: Donating a conservation easement before death reduces the property's FMV for estate purposes, since the easement restricts future development. The reduction must be supported by a qualified appraisal. See the conservation easement section below for specifics.
Annual gifting: Transferring property interests during life using the annual gift tax exclusion reduces the gross estate over time. Gifts of fractional interests in real property require qualified appraisals to establish the value of each transferred interest.
Marital deduction: Property passing to a surviving U.S. citizen spouse qualifies for the unlimited marital deduction and is excluded from the taxable estate entirely. This defers, rather than eliminates, the estate tax to the surviving spouse's estate.
What are the special rules for properties with conservation easements?
A conservation easement is a legal restriction on a property's use, typically donated to a qualified land trust or government entity. When a property subject to a conservation easement is included in an estate, the FMV for estate purposes reflects the restricted use, not the property's development potential.
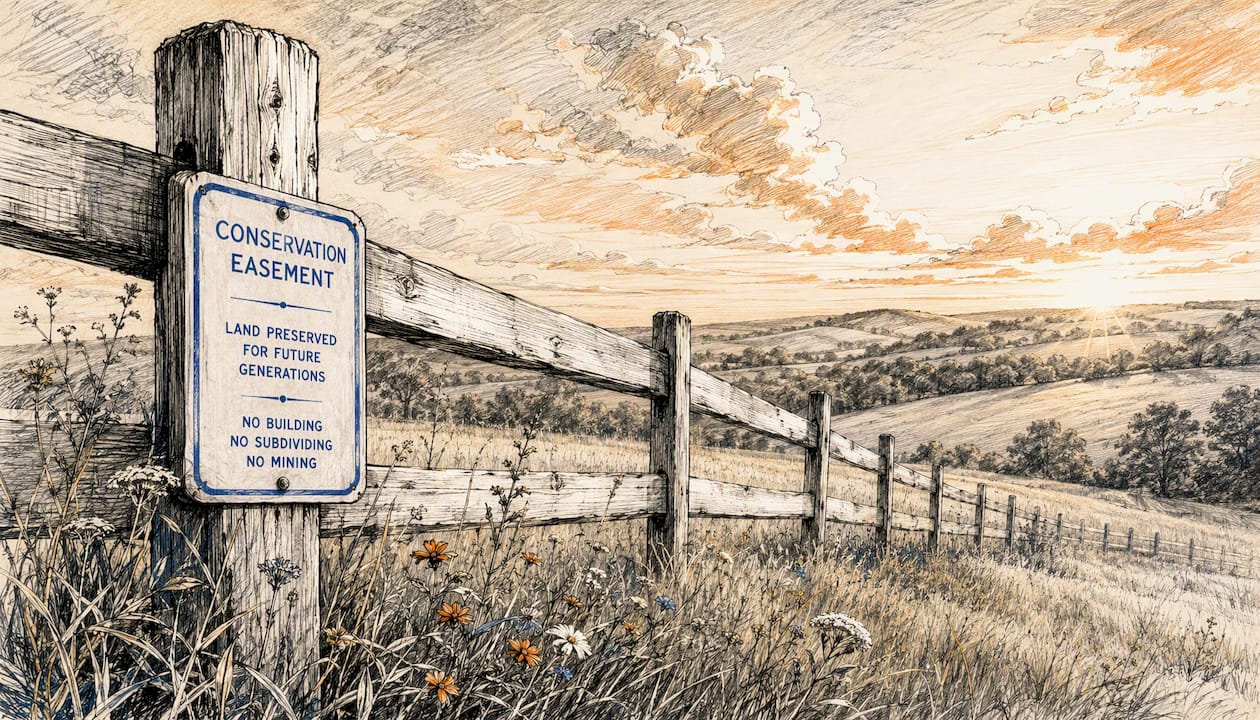
The difference between the unrestricted FMV and the restricted FMV is the easement's value. For estate purposes, the property is valued in its restricted state. This can significantly reduce the gross estate, particularly for large rural or agricultural parcels in New Jersey counties like Hunterdon, Sussex, or Burlington.
Key appraisal requirements for easement properties:
- The appraisal must value the property in its restricted state as of the date of death.
- A "before and after" analysis (unrestricted value minus restricted value) is typically required to document the easement's impact.
- The appraiser must be familiar with conservation easement valuation methodology and the specific restrictions in the easement deed.
Easement properties are among the most complex to appraise for estate purposes. The IRS scrutinizes these valuations closely, and an appraiser without specific easement experience can produce a report that invites challenge. For NJ properties with easements held by the New Jersey Conservation Foundation or the State Agriculture Development Committee (SADC), the appraiser should be familiar with the specific easement terms and local market conditions.
How do you handle heir disputes over property valuation and allocation?
Disputes among heirs over property valuation are more common than most families expect, particularly when one heir wants to keep the property and others want to sell. The allocation between land and improvements adds another layer of potential disagreement, since it directly affects the depreciation benefit available to whoever inherits the rental income.
Steps to reduce dispute risk:
- Commission a USPAP-compliant appraisal early in the estate process, before distributions are discussed. An independent, state-certified appraisal gives all parties a credible starting point.
- Provide all heirs with a copy of the appraisal report and the Schedule A (Form 8971) values. Transparency reduces the perception that one heir is being favored.
- If heirs disagree with the appraised value, they may commission their own appraisal. When two appraisals diverge significantly, a third appraiser can be appointed as an umpire, a process sometimes specified in the estate instrument.
- Mediation is often faster and less expensive than probate litigation. An estate attorney can facilitate a structured negotiation using the appraisal as the factual anchor.
When disputes reach probate court, the judge will typically rely on the appraised values from qualified, state-certified appraisers. An appraisal that follows USPAP, documents its methodology, and is prepared by a credentialed appraiser carries significantly more weight than an informal estimate or an assessor's value. The role of appraisals in NJ estate settlement is well-established in probate proceedings across all 21 counties.
Our perspective on estate allocations in New Jersey
Working across all 21 New Jersey counties, we see the same problems repeat in estate after estate. The most common: an executor uses the county assessor's land/improvement ratio without checking whether it reflects the property's actual condition as of the date of death. In high-value suburbs like Short Hills (Morris County) or Ridgewood (Bergen County), assessor ratios can be years behind market reality. A property that sold for $1.2 million may have an assessor ratio built on a mass-appraisal model that hasn't been updated since the last revaluation cycle. That ratio, applied to a $1.2 million FMV, can produce a building basis that's off by $100,000 or more.
We also see conservation easement properties handled without appraisers who understand the specific SADC or Green Acres restrictions. The easement deed matters. Two properties in Hunterdon County with similar acreage can have very different restricted values depending on the easement's terms, and a generic appraisal won't capture that.
Our approach is straightforward: we prepare the retrospective date-of-death appraisal with a clear effective date, a documented land/improvement breakout, and a methodology explanation that holds up under IRS review. We work directly with estate attorneys and CPAs to coordinate the appraisal with Form 706 preparation, so the values are consistent across all filings. If you're managing an estate in New Jersey and need a defensible allocation, call us before you file.
Newjerseyrealestateappraisal delivers court-ready estate appraisals across New Jersey
When the estate includes real property and the allocation needs to hold up to IRS scrutiny, probate court, or a dispute among heirs, you need more than a number. You need a report.

Newjerseyrealestateappraisal provides state-certified, USPAP-compliant date-of-death and estate appraisals for executors, estate attorneys, and CPAs throughout New Jersey. With 26+ years of combined experience across all 21 NJ counties, we deliver court-ready reports that include a clear effective date, a documented land/improvement breakout, methodology reconciliation, and workpapers your CPA can use directly in Form 706 preparation. Turnaround typically runs 2–4 weeks for standard residential properties, with complex or multi-property estates handled on a coordinated timeline.
Ready to get started? Request your estate and date-of-death appraisal online or call us at (908) 517-3913. We'll confirm scope, timeline, and fees before any work begins.
Sources
The following IRS publications and guidance documents are the primary authorities for estate property allocation in the United States:
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.