
A market rent analysis appraisal delivers one number: the monthly rent a specific property would command in the current leasing market, backed by adjusted comparables and, in many cases, a formal income analysis. If the report will support a lending decision, a court filing, a tax appeal, or an estate matter, it needs to be a USPAP-compliant appraisal from a state-certified appraiser, not a quick rent survey. A rent study or CMA works fine for pricing a listing.
Three things make a rent conclusion defensible: a properly selected set of comparables, correct adjustments for physical and economic differences, and a reconciliation that explains how the appraiser landed on the final figure. Every credible report built to Fannie Mae Multifamily or USPAP standards includes all three.
- Definition: one evidence-backed rent figure from adjusted comps, plus income modeling when the assignment calls for it.
- When you need USPAP: lending, litigation, divorce, estate, and tax appeal work.
- When a rent study is enough: pre-listing pricing or an internal check with no legal or lending weight.
- Who does this in New Jersey: Newjerseyrealestateappraisal, state-certified across all 21 counties.
TL;DR:
- Use at least four verified rental comparables from reliable sources like rent rolls or signed leases, with physical and economic adjustments documented clearly.
- Adjust effective rent for concessions and recent lease terms, and apply market rent only to vacant or soon-to-expire units to avoid overestimating value.
- Follow USPAP and lender standards by including a reconciliation, named data sources, and a signed certification to ensure the report's defensibility.
- Avoid assuming 100% market rent for all units; instead, model actual rent roll data and only project market rent for unleased or vacant units.
- Hire a certified appraiser to produce a USPAP-compliant, court- and lender-ready rent appraisal, especially for legal, financial, or tax-related decisions.
Table of Contents
- How Do Appraisers Select Rental Comparables?
- What Is Effective Rent and How Do You Calculate It?
- Why Is 100% Market Rent Usually the Wrong Number?
- Which Standards Does a Defensible Rent Appraisal Follow?
- USPAP Appraisal or Rent Study: Which One Do You Need?
- What the Standards Get Right, and What Most Guides Skip
- Get a State-Certified Market Rent Appraisal From Newjerseyrealestateappraisal
- Key Takeaways
- Sources
How Do Appraisers Select Rental Comparables?
Comp selection makes or breaks a rent conclusion. Weak comps produce a number nobody can defend in front of a lender, a judge, or a tax board.
Fannie Mae's multifamily guidance calls for multiple rental comparables, and in practice, appraisers use a sufficient number appropriate for the property size to support the conclusion.
Data sources vary in reliability. Here's how they stack up:
- Rent rolls from the subject property or nearby buildings: strong for verifying actual paid rent, weak for market context alone.
- MLS records: useful for single-family and small multifamily rentals, though rental data is often thinner than sale data.
- Signed leases: the gold standard, since they show real terms, not asking prices.
- Public records: helpful for ownership and unit mix verification, rarely for rent amounts.
- Professional rent-data services such as Rentometer or RentCast: fast for a general range, but they don't verify lease terms or concessions, and they don't substitute for a state-certified appraisal when formal documentation is required.
Timing and geography matter as much as the source. Appraisers generally prefer leases signed within the last 6 to 12 months, tightening that window in fast-moving urban submarkets and loosening it in rural areas where transactions are sparse. Geographic radius follows the same logic: a few blocks in a dense city, several miles in a low-density county.
Pro Tip: Ask any appraiser or rent-data provider whether they verified lease terms directly with the tenant, landlord, or leasing agent. Unverified online listings inflate rent estimates more often than they deflate them.
What Is Effective Rent and How Do You Calculate It?
Nominal rent and effective rent are rarely the same number, and treating them as identical is one of the fastest ways to overstate value.
Say a comparable unit lists at $2,000 a month with one month free on a 12-month lease. The tenant pays $22,000 over the year, not $24,000. Divide that by 12, and effective rent comes out to about $1,833 a month. Our guide on evaluating comparable properties walks through this math in more detail.
Once effective rent is established, the appraiser adjusts each comparable to the subject property. Common adjustment categories include:
- Unit size and bedroom/bathroom count
- Condition and recent renovations
- Amenities (in-unit laundry, parking, storage, outdoor space)
- Floor level and view
- Utilities included versus tenant-paid
- Parking availability and type
Economic adjustments sit on top of these physical ones. Vacancy trends, how common concessions are in the submarket, and any rent stabilization or regulation affecting the comparable all get documented. A 50% concession rate across a comp set signals a soft rental market and demands a downward adjustment that a rent conclusion ignoring effective rent would miss entirely. Every adjustment, physical or economic, needs a stated rationale. "We adjusted it down" isn't documentation; "adjusted $75 for the absence of assigned parking, based on three comps with and without" is.
Why Is 100% Market Rent Usually the Wrong Number?
Plugging every unit into a pro forma at full market rent looks clean on paper. It's also, in most cases, not how a competent appraisal works.
Freddie Mac's guidance is direct on this point: for stabilized multifamily properties, modeling 100% market rent instead of the actual rent roll isn't compliant. The correct approach uses the current rent roll for occupied units and market rent only for vacant units.
This is where loss-to-lease comes in. Loss-to-lease is the gap between what a unit could rent for today and what the current tenant actually pays under an existing lease. For an as-is appraisal, assuming every lease instantly resets to market rent is usually an invalid hypothetical. The property doesn't turn over that fast, and the value opinion has to reflect what's actually collectible.
- Document the current rent roll unit by unit.
- Apply market rent only to vacant or soon-to-expire units.
- Explain any material gap between contract rent and market rent. That gap directly affects leased fee value, and reviewers expect a narrative, not a silent number.
Our income approach guide for NJ investors breaks down how PGI and EGI flow from this rent roll into a full income analysis.
Which Standards Does a Defensible Rent Appraisal Follow?
A market rent conclusion isn't just a well-argued opinion. It has to meet specific professional and lender standards, or it gets rejected the moment someone checks it.
USPAP Standards 1 and 2 require appraisers to collect and verify enough data for credible results, then report those findings in a way consistent with the standard. That's the baseline for any assignment that qualifies as an appraisal, including a market rent analysis used to establish fair value.
Lender-specific guidance adds detail on top of that baseline. Fannie Mae's multifamily requirements call for identified primary data sources, discussion of rental competition, a clear explanation of contract rent versus market rent, and a feasibility analysis when the property is new construction or recently rehabbed.
Run any report against this checklist before you rely on it:
- At least four rental comparables, more for larger properties.
- Data sources named, not just numbers presented.
- Effective rent calculated wherever concessions exist.
- Feasibility analysis included for new or rehabbed properties.
- A reconciliation section explaining how the final rent figure was reached.
- A signed certification statement confirming USPAP compliance.
- Missing even one of these items gives a lender, attorney, or tax board a reason to send the report back.
USPAP Appraisal or Rent Study: Which One Do You Need?
Not every situation calls for a full USPAP appraisal, and paying for one when a rent study would do just wastes money.
A formal appraisal is mandatory when a lender is underwriting a loan, a court needs a defensible number for divorce or estate proceedings, or you're filing a New Jersey property tax appeal. Anywhere the number faces outside scrutiny, you need the certified version.
A rent study or CMA is fine for pre-listing pricing, internal portfolio checks, or a landlord deciding on a renewal rate with no legal exposure. It's faster and cheaper, but it carries no weight in a legal or lending context.
Turnaround and cost track complexity. A single-family rental appraisal often falls in the $200 to $1,000 range with a 3 to 14 business day turnaround; multifamily properties take longer and cost more depending on unit count and how organized the property's records are.
To speed things up, hand your appraiser:
- Current rent roll
- Copies of active leases
- Service and utility contracts
- Records of recent capital improvements
What the Standards Get Right, and What Most Guides Skip
Most online guidance on rent analysis treats comp selection as the whole job. It isn't. The comps matter, but the reconciliation, the part where an appraiser explains why the final number sits where it does, is what actually holds up under a lender's review or a judge's questions.
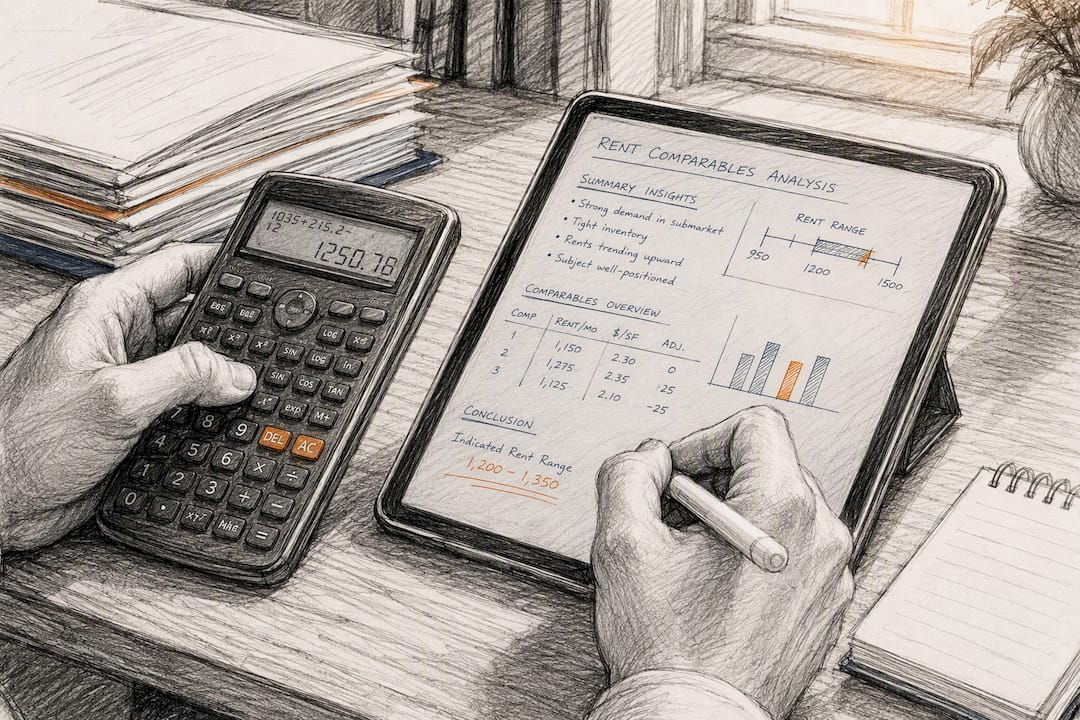
The biggest gap I see in casual rent studies is loss-to-lease. Plenty of investors and even some agents build pro formas at 100% market rent because it's the more attractive number, and it just doesn't match how Freddie Mac or any credible appraiser actually models income for a stabilized property. If your rent conclusion doesn't account for what's actually collectible today, it's a projection, not an appraisal.
Prioritize verification over volume. Four well-verified, well-adjusted comparables with documented lease terms beat ten scraped listings every time. That's the part conventional advice glosses over, and it's exactly where a state-certified appraiser earns the fee.
— Alek
Get a State-Certified Market Rent Appraisal From Newjerseyrealestateappraisal
Newjerseyrealestateappraisal has spent over 26 years producing USPAP-compliant reports across all 21 New Jersey counties, and we build every market rent conclusion the way a lender, a judge, or a tax board expects to see it: verified comps, documented adjustments, and a reconciliation you can defend.

We handle divorce, estate, tax appeal, and lending-related rent appraisals across the state, from Atlantic County to Union County. Send us your rent roll, current leases, intended use, and deadline, and you'll get a full comps list, documented adjustments, an income reconciliation, and a signed USPAP certification back.
Ready to get a defensible number instead of a guess? Visit our appraisal services page or call us at (908) 517-3913 to start your market rent appraisal today.
Key Takeaways
A defensible market rent appraisal combines verified comparables, documented effective-rent adjustments, and a reconciliation that ties them to a single, standards-compliant rent figure.
| Point | Details |
|---|---|
| Know which report you need | USPAP appraisals apply to lending, court, estate, and and tax appeal cases; rent studies suit pre-listing pricing only. |
| Use enough comparables | Aim for at least four verified rental comps, following Fannie Mae's multifamily guidance. |
| Convert to effective rent | Factor in concessions like free months before comparing any listed or contract rent. |
| Model income realistically | Use the current rent roll plus market rent for vacant units instead of assuming 100% market rent. |
| Work with a certified provider | Newjerseyrealestateappraisal delivers USPAP-compliant, court- and lender-ready reports across all 21 NJ counties. |
Sources
- Fannie Mae Multifamily — guidance and requirements
- Freddie Mac Multifamily appraisal guidance — modeling potential gross income
- Market Rent Appraisal: How fair market rent is determined — LegalClarity