
Yes, get an FSBO appraisal before you list, especially if your property is unusual, recently renovated, or tied to a divorce, estate, or tax dispute. A state-certified appraiser working under USPAP gives you a defensible number a comparative market analysis can't match. Just know that your buyer's lender will still order its own independent appraisal at closing, so this report supports your pricing strategy rather than replacing the lender's process.
TL;DR:
- A pre-listing appraisal provides a USPAP-compliant, defensible value that can better support pricing for unique, renovated, or legally sensitive properties.
- It has a higher accuracy than free CMAs, especially for non-standard homes or in volatile markets, and can be used for marketing disclosures and negotiation leverage.
- Lenders almost never accept a seller’s appraisal during financing, but the report still helps by establishing a credible bargaining position if the lender’s appraisal is lower.
- Costs typically range from $300 to $1,000 with a turnaround of about one week, depending on property complexity, and preparation of supporting documents boosts the appraisal’s accuracy.
- Most FSBO sellers should reserve obtaining an appraisal for complicated or high-stakes sales, as it significantly reduces the risk of overpricing or dispute later in negotiations.
Table of Contents
- What Is an FSBO Appraisal, and How Is It Different From a CMA?
- When Is a Pre-Listing Appraisal Worth the Cost for FSBO Sellers?
- Will the Buyer's Lender Accept a Seller's Appraisal?
- What Does an FSBO Appraisal Cost and How Long Does It Take?
- How to Prepare Your Home and Paperwork for the Appraiser
- What to Do When the Appraisal Comes In Low
- How NJREAG Helps FSBO Sellers Get a Defensible Pre-Listing Appraisal
- How an Appraisal Shapes Buyer Interest and Negotiations
- Alternatives to a Formal Appraisal for FSBO Sellers
- Our Take: Where FSBO Sellers Get This Wrong
- Ready for a State-Certified Pre-Listing Appraisal?
- Sources
What Is an FSBO Appraisal, and How Is It Different From a CMA?
An appraisal and a CMA aren't the same tool, and confusing them is the fastest way to misprice your house.
A real estate appraisal for FSBO sellers is produced only by a state-licensed or state-certified appraiser following the Uniform Standards of Professional Appraisal Practice, or USPAP. Congress requires USPAP compliance for federally related transactions, which is why lenders trust these reports and courts accept them as evidence. A comparative market analysis, by contrast, is an informal pricing study agents put together, usually free, with no regulatory standing behind it.
A USPAP-compliant appraisal report typically includes:
- A physical inspection of the property, noting condition, layout, and systems
- A set of comparable sales with adjustments for differences
- One or more approaches to value (sales comparison is standard for homes)
- A signed certification and a scope of work disclosure explaining what the appraiser did and why
That certification matters more than most sellers realize. It's the appraiser putting their license on the line for the number, which is why appraisals hold up in lending, legal, and tax appeal situations where a CMA simply doesn't. If you just want a general sense of value to start your listing strategy, a CMA is fine. If you need a number that can survive scrutiny from a lender's underwriter or a judge, you need an appraisal.
When Is a Pre-Listing Appraisal Worth the Cost for FSBO Sellers?
Not every FSBO sale needs a paid appraisal. But in certain situations, skipping one is a costly mistake.
Get a pre-listing appraisal when:
- Your property is unique or hard to comp, like a converted barn, a waterfront lot, or a home with an unusual floor plan.
- You've made major renovations, especially ones without permits, where an agent's CMA tool won't capture the added value correctly.
- The sale is tied to a divorce, estate, or property tax appeal, where a defensible, USPAP-compliant number carries legal weight a CMA can't provide.
- You're selling in a fast-moving or volatile local market where recent comps are already stale.
A free CMA or an online estimator can be enough for a straightforward, cookie-cutter home in a stable, well-comped neighborhood. The tradeoff is accuracy: automated tools can't see your finished basement or your outdated bathroom, and they routinely miss by a wide margin on non-standard properties.
Beyond pricing, a pre-listing appraisal gives you language and documentation for marketing disclosures, and it gives you leverage when a buyer's agent tries to talk your price down without any data to back up their claim.
Pro Tip: Order the appraisal before you set your listing price, not after. Retrofitting a price to match an appraisal you get midway through negotiations looks defensive instead of confident.
Will the Buyer's Lender Accept a Seller's Appraisal?
Almost never, and you should plan around that fact instead of being surprised by it.
When a buyer finances the purchase, their lender selects or approves the appraiser, and the buyer typically pays for that appraisal. Lenders require an independent appraiser specifically because USPAP's neutrality standards are what let them trust a value opinion they didn't influence. Your seller-ordered appraisal, no matter how solid, doesn't satisfy that requirement.
A few regulatory nuances are worth knowing:
- Federal rules set a residential de minimis threshold of $400,000, below which lenders may use appraisal alternatives instead of a full appraisal.
- Even under that threshold, lenders often still order full appraisals based on internal policy or secondary market requirements from Fannie Mae or Freddie Mac.
- Desktop and hybrid appraisals, where a physical inspection is skipped or limited, are becoming more common alternatives, and the report should disclose which method was used.
Your seller-ordered appraisal still earns its keep. It's the pricing evidence you bring into negotiations, and it becomes ammunition if the lender's appraisal later comes in low. It just won't substitute for the lender's own independent report.
What Does an FSBO Appraisal Cost and How Long Does It Take?
Budget and timeline questions come up early for most FSBO sellers, and the answers are more predictable than people expect.
Fee range: A standard single-family appraisal commonly runs $300 to $600, climbing toward $1,000 for larger, more complex, or unusually located properties. Rush requests add a premium on top of that.
Timeline: Most appraisers schedule an inspection within a week of the order, with the finished report following three to seven days after that. Complex properties or backlogged markets can stretch it longer.
- Standard single-family home: $300–$600
- Complex, large, or rural properties: up to $1,000
- Desktop or hybrid appraisals: often cheaper, but they trade some accuracy for speed since they involve limited or no physical inspection
If your timeline is tight, ask upfront whether a full inspection appraisal or a hybrid option makes more sense for your situation.
How to Prepare Your Home and Paperwork for the Appraiser
An appraiser walks in with a blank scope of work and a job to do. Your prep work determines how efficiently, and how accurately, they can do it.
Assemble these before the appointment:
- Permits for any structural, electrical, or plumbing work
- Receipts for major upgrades, with dates and costs attached
- HOA documents if applicable, including fees and any special assessments
- A short list of recent sales nearby that you believe are genuinely comparable
- A floor plan, if you have one, especially for homes with additions or unusual layouts
On the home itself, clear clutter, make sure every room and mechanical system is accessible, and have service records handy for the furnace, roof, and water heater. Treating the visit like a professional inspection rather than a showing measurably reduces friction and helps the appraiser reach a well-supported number.
Be honest about your comparables and disclosures. Overstating an upgrade's cost or quality doesn't move the appraiser's opinion, since they verify claims against permits and market data anyway.
Pro Tip: Write a one-page upgrade summary with dates and costs instead of handing over a shoebox of receipts. Appraisers can weigh documented, itemized information far faster than a pile of paper.
What to Do When the Appraisal Comes In Low
A low appraisal isn't the end of your sale, but it does require a clear-headed plan instead of panic.
Work through these steps in order:
- Review the report line by line for factual errors: wrong square footage, missed bedrooms, incorrect lot size, or outdated comps.
- Compile comparable sales the appraiser may have genuinely missed, not just properties you personally think are similar.
- Submit a formal reconsideration of value request with that documentation attached.
- If reconsideration doesn't move the number, negotiate contract terms, such as splitting the gap or adjusting the price.
- Consider a second appraisal opinion if the first one seems clearly off base and the stakes justify the extra cost.
Reconsideration requests succeed most often when they bring genuinely new comparable sales or correct factual errors, not when they argue opinion against opinion. Appraisers operate under USPAP's independence rules, so they aren't obligated to change a supported conclusion just because a seller disagrees with it. If your comps and corrections are solid, push for reconsideration. If they're not, adjusting your price is usually the faster path to closing.
Pro Tip: Lead your rebuttal with the strongest missed comparable first. Appraisers reconcile value by weighing comps with adjustments, so one excellent overlooked sale beats five weak ones.
How NJREAG Helps FSBO Sellers Get a Defensible Pre-Listing Appraisal
We're New Jersey Real Estate Appraisal Group, a state-certified appraisal firm with more than 26 years of combined experience across all 21 New Jersey counties. Every report we produce for FSBO sellers is USPAP-compliant, which means it holds up under scrutiny from lenders, buyers' agents, and, if needed, a courtroom.
For FSBO sellers, our typical deliverable is a pre-listing Appraisal Report, built on a full property inspection and a set of verified local comparables. We also offer a Restricted Appraisal Report for lower-stakes internal use, where a full narrative isn't necessary. Turnaround typically runs about a week from inspection to final report, in line with standard industry timelines.
Ordering is simple: call us or request an appraisal online, and we'll walk you through scheduling and what documentation to have ready. Divorce, estate, and tax appeal appraisals are our specialty, so if your FSBO sale touches any of those situations, we've handled it before.
How an Appraisal Shapes Buyer Interest and Negotiations
A pre-listing appraisal changes the tone of every conversation you have with a buyer, and it usually changes it in your favor.
Buyers and their agents test FSBO prices harder than agent-listed ones, assuming an unrepresented seller either overpriced out of emotion or underpriced out of inexperience. Walking into negotiations with a state-certified appraisal in hand removes that assumption immediately. It signals you did the homework a listing agent normally would, and it gives buyers' agents a credible number they can bring back to their own client instead of pushing back with a lowball offer.
The dynamic shifts again once the buyer's lender orders its own appraisal. If that number lands close to yours, your pre-listing report gets validated retroactively and the deal moves forward with confidence on both sides. If the lender's appraisal comes in lower, your original report becomes the foundation for a reconsideration request or a renegotiation, rather than starting that conversation from zero.
There's a psychological factor here too. Buyers who see a professional appraisal feel less like they're negotiating against a stranger's guess and more like they're responding to a documented market position. That perception alone reduces lowball offers and speeds up serious buyers' decision-making, even before the lender's appraisal enters the picture.
Alternatives to a Formal Appraisal for FSBO Sellers
An appraisal isn't your only option, and for some sellers, it isn't the right first step.
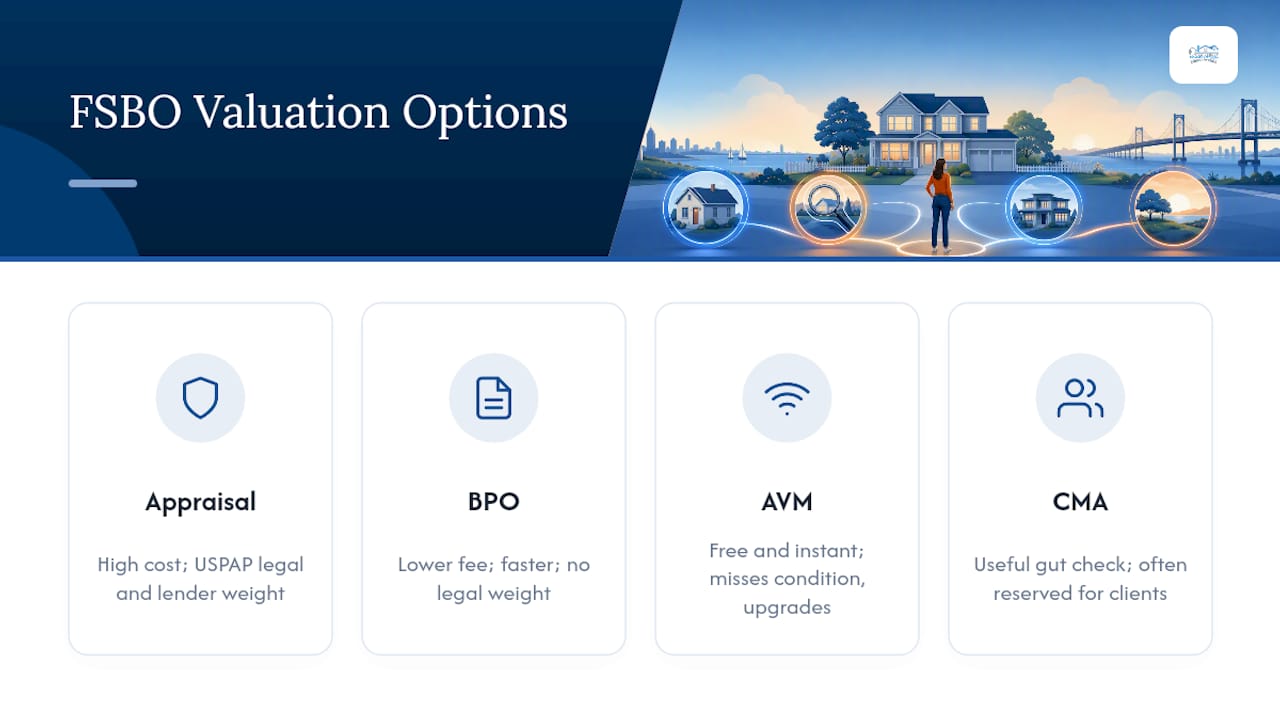
A broker price opinion, sometimes offered by agents for a smaller fee than a full appraisal, gives a professional's read on value without the full USPAP process behind it. It's faster and cheaper, but it carries none of the legal or lending weight a certified appraisal does.
Online valuation tools, often called automated valuation models, pull recent sales data and algorithmically estimate your home's worth. They're free and instant, which makes them tempting, but they routinely miss condition issues, upgrades, and neighborhood nuances that only a human inspection catches. Treat their number as a starting point for research, not a pricing decision.
A traditional CMA from a local agent, even one you're not hiring to list your home, can offer a useful gut check, though most agents reserve this for active clients.
For a low-stakes, standard property in a stable market, one of these lighter options might be all you need to set an initial price. But the moment your situation involves legal proceedings, tax disputes, unusual property features, or real money on the line, the gap between a free estimate and a certified appraisal stops being about convenience and starts being about risk.
Our Take: Where FSBO Sellers Get This Wrong
Most FSBO advice treats appraisals as optional paperwork instead of a decision tool. That's backward. The research here supports a narrower, more useful conclusion: get the appraisal when your situation has legal, financial, or pricing complexity, and skip it when your home is a straightforward comp in a stable neighborhood.
The bigger mistake we see is sellers assuming a strong pre-listing appraisal protects them from a low lender appraisal later, so learning how to sell your home without a real estate agent can also help you navigate these challenges more effectively. It doesn't. What it does is arm you with documentation and a credible number to negotiate from, which is a real advantage most FSBO sellers walk into a sale without.
Prioritize preparation over hope. Appraisers reconcile value with comps and adjustments, not sentiment, so a seller who shows up with permits, upgrade records, and legitimate comparables consistently gets a more defensible number than one who just opens the door and expects the house to speak for itself.
— Alek
Ready for a State-Certified Pre-Listing Appraisal?
If you're selling FSBO anywhere in New Jersey, a state-certified pre-listing appraisal from NJREAG gives you a number a buyer's lender, agent, or attorney can't easily dismiss, and it costs a fraction of what a bad pricing mistake costs you at closing.

Getting started is straightforward. Call us at (908) 517-3913, or request your appraisal directly through our Union County appraisal services page if you're selling in that area. We'll confirm scheduling, tell you exactly what documentation to pull together, and get your inspection on the calendar, usually within the week. If your sale involves an estate, divorce, or tax appeal on top of the FSBO listing, mention it when you call so we can scope the report correctly from the start.
Sources
- USPAP Compliance Checklist: Scope, Ethics, and Reporting - LegalClarity
- Realtor
- Home appraisal checklist - Investopedia